Written byTim HighlandGroup President – Wealth Management
Updated on
“We’ll just use Claude directly” is one of the most common responses firms have when evaluating AI adoption right now. It’s an understandable instinct — the model is powerful, the sticker price looks simple, and it feels like the leaner option next to buying a full platform. It’s also, in almost every case, more expensive than it looks.
What the surface-level cost actually includes
Using Claude for Financial Advisors directly typically requires a Claude Cowork subscription and an Enterprise license. Industry estimates already put the realistic, fully-loaded cost at roughly $70 to $120 per user per month — before a firm has built a single custom workflow. That’s the starting line, not the total.
What the DIY price tag doesn’t show you
The real cost of a do-it-yourself AI workflow shows up after the subscription is signed:
Integration engineering. Connecting Claude to a custodian, a CRM, a planning tool, and a compliance system isn’t a checkbox — it’s ongoing engineering work, often requiring dedicated technical staff or expensive contractors to build and maintain each connector as vendor APIs change.
Compliance review, repeated. Every new data source or workflow touching client information needs its own compliance and security review. A DIY build means a firm’s compliance team is auditing a patchwork of custom integrations instead of one governed system.
Maintenance debt. DIY workflows don’t stay finished. APIs change, models get updated, connectors break. Someone has to own that upkeep indefinitely, and that someone is usually an internal hire whose time now has an opportunity cost.
No vendor accountability. When a purpose-built platform gets something wrong, there’s a vendor responsible for the fix. When a firm has assembled its own workflow around Claude, the firm owns the failure — including, in a regulated industry, the liability question of who’s responsible when an AI-assisted output turns out to be wrong.
Advisor time lost to workarounds. A DIY workflow rarely covers every edge case on day one. Every gap becomes a manual workaround an advisor has to perform — quietly eating into the very time savings AI was supposed to deliver.
A rough comparison
Cost category
DIY (Claude direct)
Purpose-built platform (JIFFYAI)
Base subscription
~$70–$120/user/month
Platform-based, typically bundled
Integration build
Ongoing engineering cost, per connector
Included, pre-built and maintained
Compliance review
Repeated per data source
Single governed compliance surface
Maintenance
Owned internally, indefinitely
Owned by the vendor
Liability on errors
Held by the firm
Shared contractually with the vendor
Time to full deployment
Months, often longer
Weeks
The line items on the left rarely make it into the initial budget conversation — which is exactly why DIY looks cheaper than it turns out to be.
The real question isn’t cost. It’s total cost of ownership.
A firm evaluating “Claude alone” versus a purpose-built platform like JIFFYAI shouldn’t be comparing subscription prices. It should be comparing total cost of ownership over 12–24 months, including engineering time, compliance overhead, maintenance burden, and the advisor hours lost to gaps a DIY build hasn’t yet covered. When firms run that full comparison, the “cheaper” DIY option is very often the more expensive path — just with its costs spread out and harder to see upfront.
Unlock the potential of AI-powered transformation.
Written byManish PandeyChief GTM & Marketing Officer
Updated on
There’s a temptation, whenever a new AI platform enters wealth management, to frame it as a challenger to whatever frontier model is making headlines. That framing misses the point. Claude is genuinely excellent at what it does — reasoning over complex financial information, drafting client-ready documentation, following nuanced instructions. The question a firm should actually be asking isn’t “Claude or something else?” It’s “what does Claude need underneath it to work at its best, every day, across our entire book of clients?”
That’s the problem JIFFYAI is built to solve. Not a replacement for Claude. The foundation that makes Claude — or any model a firm chooses to run — actually complete.
Intelligence needs a foundation
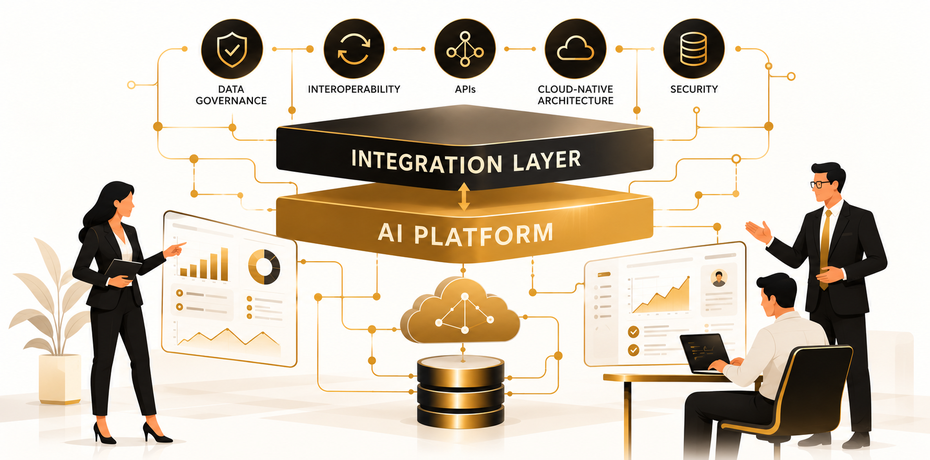
A foundation model like Claude is remarkably capable at reasoning and language. What it doesn’t inherently have is a firm’s unified, real-time picture of a client: custodial holdings, CRM history, past meeting notes, email context, compliance requirements, household relationships — all reconciled into one coherent record. Without that foundation, even the best model is only ever answering from whatever slice of data it happens to be connected to at the moment.
JIFFYAI’s role is to be that foundation. It unifies a firm’s data — across custodians, CRMs, communications, and compliance systems — into a single, governed layer, and then lets an advisor bring any AI model, including Claude, to bear on top of it with full context, not fragments.
What this looks like in practice
Instead of an advisor pinging Claude through one connector for portfolio data, another tool for CRM notes, and a separate workflow for compliance review, JIFFYAI gives the model one consistent, real-time view of the client to reason over. The result is fewer blind spots, faster answers, and a single compliance and data-governance surface — instead of a separate one for every connector a firm has stitched together.
This is the same logic other serious players in this space have already put into practice: unify the data first, then let best-in-class AI models operate on top of that unified foundation, rather than trying to make the model itself do the job of a data platform. It’s a validated approach — and it’s the one JIFFYAI is built around.
Not a threat. A force multiplier.
Positioning JIFFYAI as “anti-Claude” would be both inaccurate and strategically shortsighted. Claude is a genuinely strong reasoning engine, and firms are right to want access to it. JIFFYAI’s value isn’t in competing with that intelligence — it’s in making sure that intelligence is working from a complete, accurate, and compliant picture of every client a firm serves, instead of whatever one connector happens to expose in the moment.
Firms that get this right won’t be choosing between JIFFYAI and Claude. They’ll be running both, together, and getting more out of each than either could deliver alone.
Unlock the potential of AI-powered transformation.
Written byTim HighlandGroup President – Wealth Management
Updated on
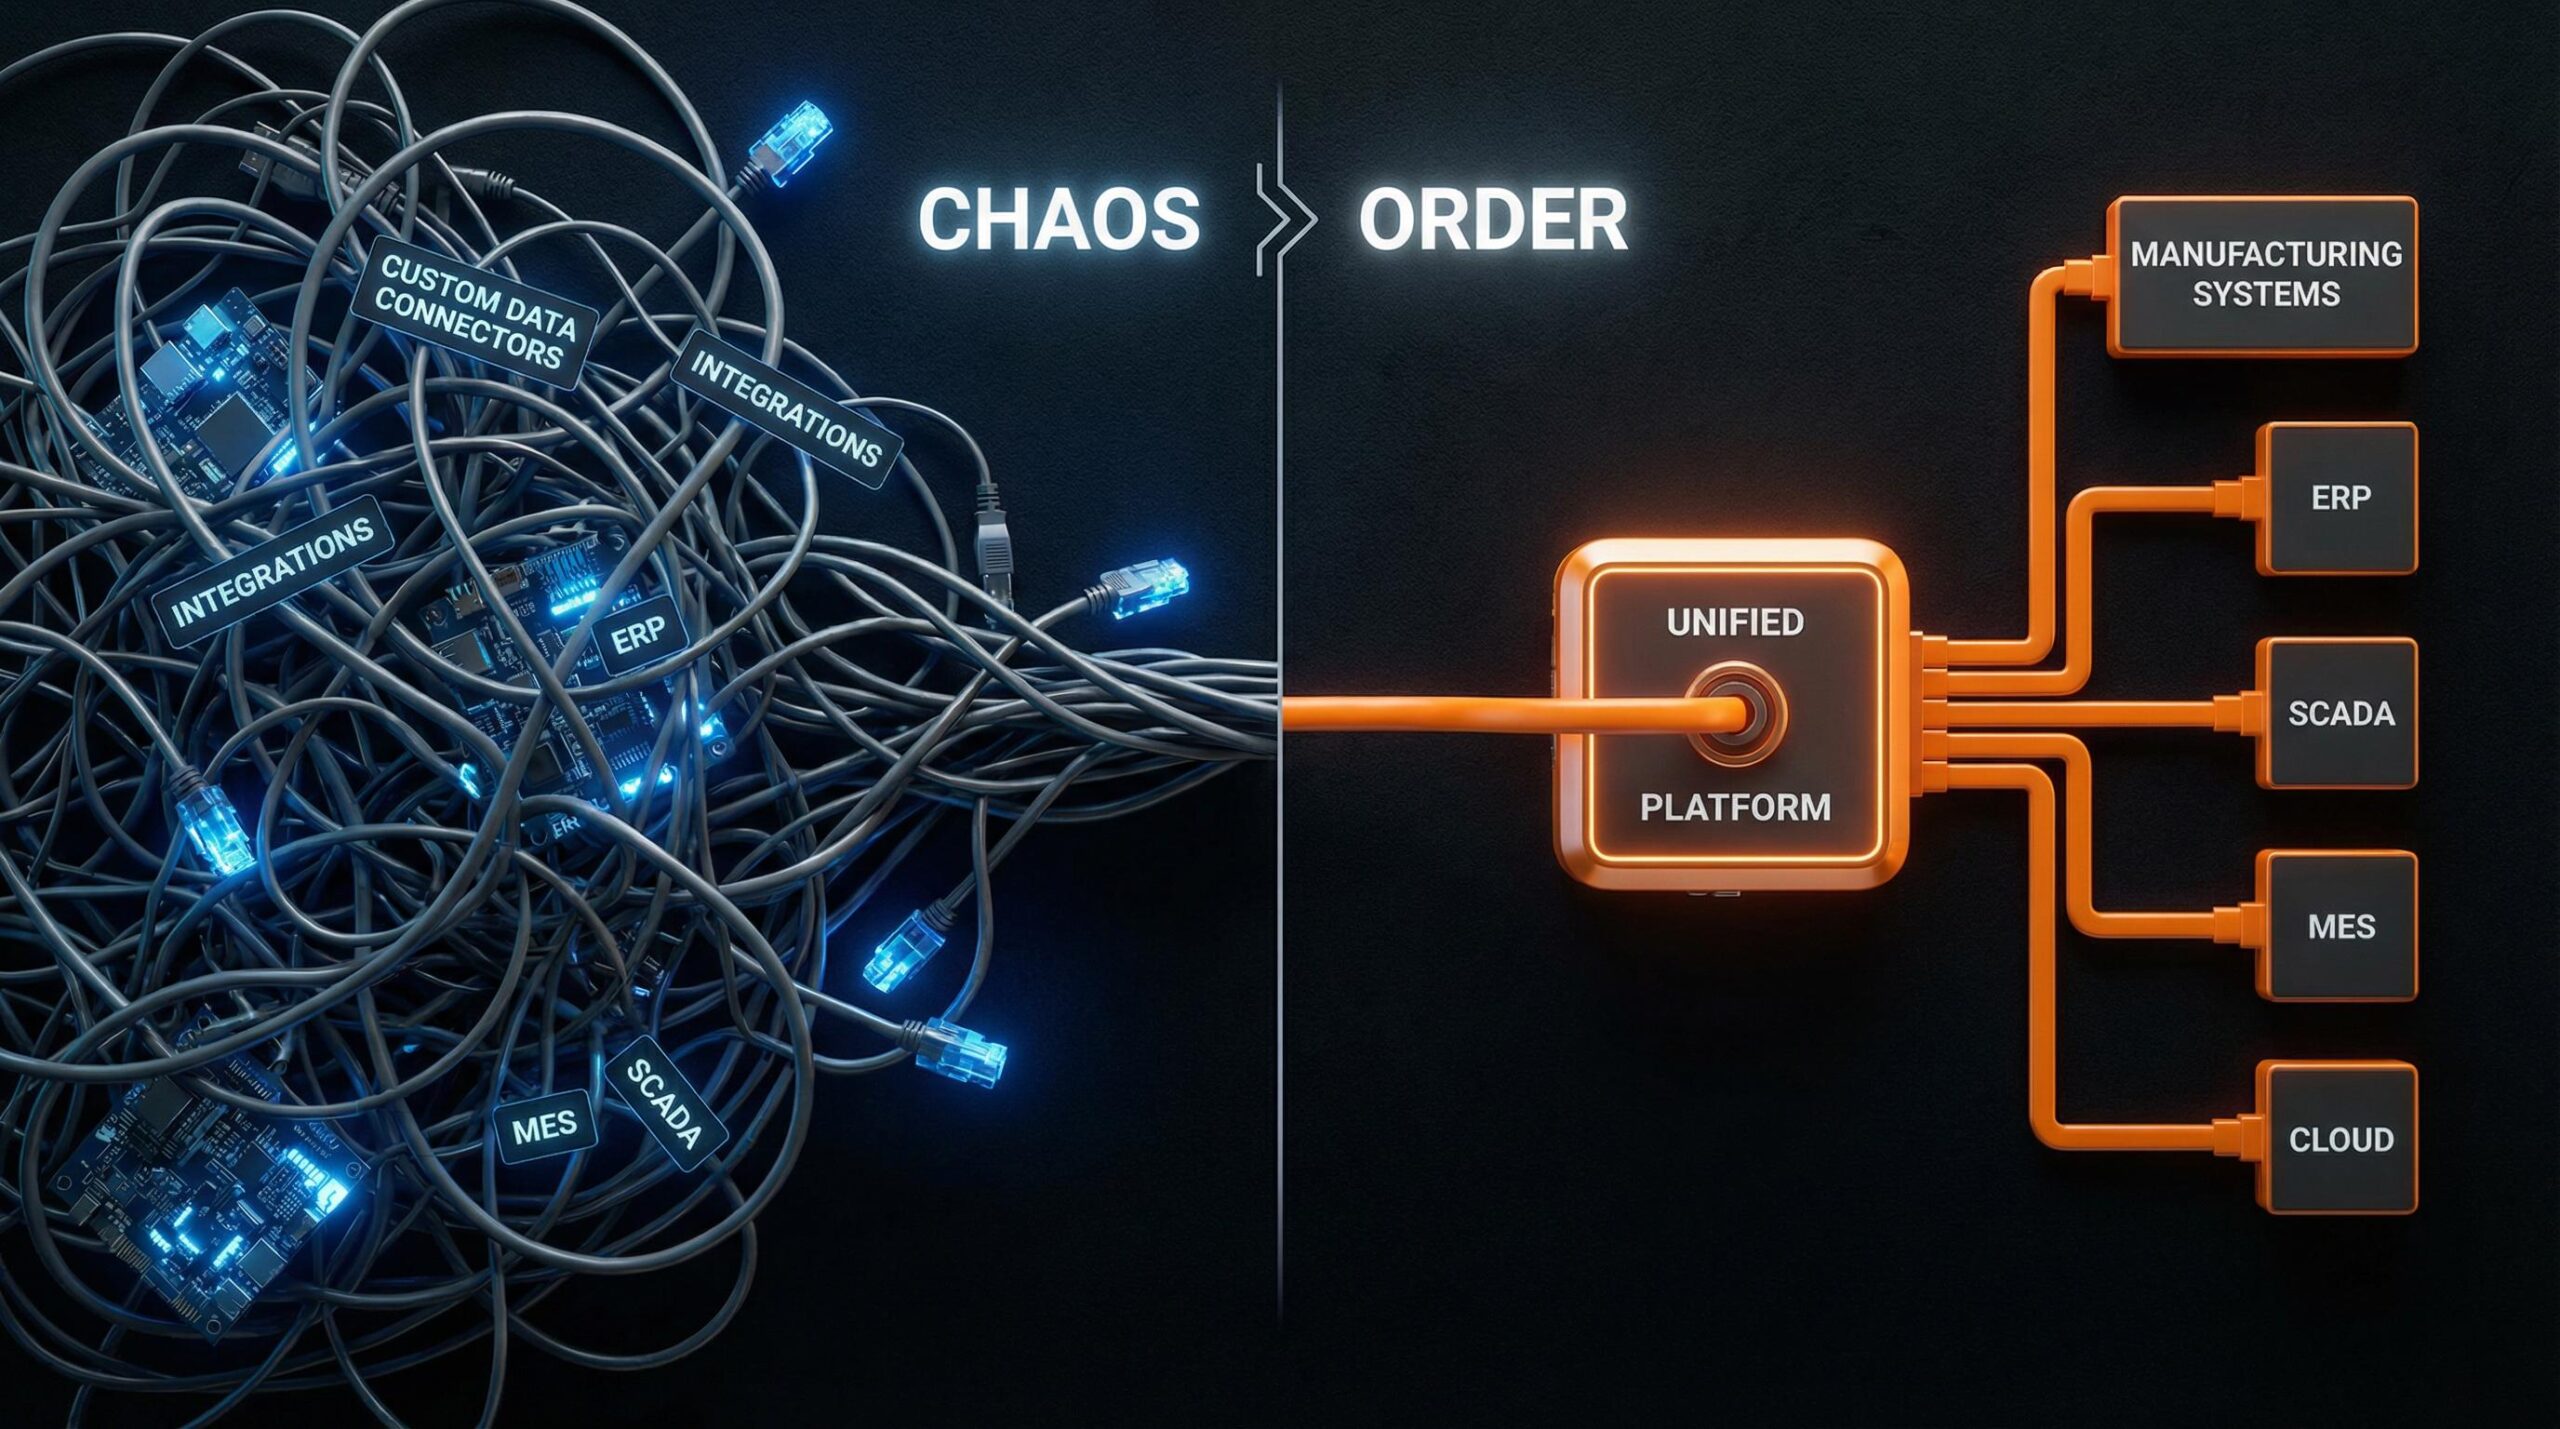
Every AI vendor entering wealth management right now is telling advisors the same story: adopt us, and get hours back. Few of them are telling advisors the second half of that story — that stacking five or six of these tools on top of an already-fragmented tech environment creates a new kind of drag that quietly erodes the time savings.
The firms pulling ahead in this cycle aren’t the ones with the most AI subscriptions. They’re the ones treating unification — one system, one data layer, one workflow — as the actual strategic asset.
The plugin model has a ceiling
Most of the current wave of AI adoption in wealth management follows the same pattern: take a foundation model, connect it to a custodian here, a CRM there, a planning tool somewhere else. It works, and it’s a real improvement over doing everything manually. But it has a structural ceiling, because every connector is a separate integration, a separate point of failure, and a separate thing that can fall out of sync.
Advisors end up with an assistant that’s smart in isolation but incomplete in practice — because it only ever sees one system at a time, and the advisor is still the one reconciling what doesn’t match across tools.
What “unified” actually means
A genuinely unified system isn’t just a dashboard that displays data from multiple sources. It means:
One data layer — client data, portfolio data, CRM notes, and communications live in a single coherent model, not five databases stitched together after the fact.
One workflow engine — meeting prep, follow-ups, compliance checks, and reporting run through the same system, so nothing has to be manually copied between tools.
One compliance surface — a single vendor relationship, a single data-sharing agreement, a single audit trail, instead of a separate review for every point solution.
One place advisors actually work — not a tab for the AI assistant, a tab for the CRM, and a tab for the custodian portal.
The ROI case is bigger than time savings
The obvious pitch for AI in wealth management is time recovered from documentation and prep. That’s real, but it understates the case for unification specifically. A single unified system also reduces:
Integration cost — no ongoing engineering effort to maintain a dozen separate connectors as each vendor updates its API.
Data risk — fewer places client PII lives, fewer vendors with access to it, fewer points of failure.
Training and change management overhead — advisors learn one system, not a rotating set of point tools.
Decision latency — when data lives in one place, an advisor (or their AI assistant) gets a complete answer immediately, instead of a partial one that needs to be cross-checked.
Signs your firm needs to consolidate, not add another tool
Your team is logging into more than three separate systems to prepare for a single client meeting.
Compliance review time has grown faster than advisor headcount.
Two tools in your stack sometimes disagree about the same client data.
Every new AI tool pitch sounds appealing, but you can’t clearly say what it replaces.
If any of that sounds familiar, the answer isn’t a better point solution. It’s fewer, more unified ones.
Unlock the potential of AI-powered transformation.
Written byManish PandeyChief GTM & Marketing Officer
Updated on
Wealth management is in the middle of an AI land rush. In the space of a few months, Anthropic launched Claude for Financial Advisors with more than a dozen launch partners. OpenAI followed days later with its own competing financial services package. Altruist expanded its Hazel platform into tax planning and financial planning agents. LPL, Orion, Schwab, and Vanguard all announced their own AI integrations. On one single day in February, the launch of an AI tax tool by a challenger custodian was enough to send shares of LPL, Schwab, and Raymond James down 7–8%.
That’s not a market maturing calmly. That’s a market moving so fast that even the firms driving it are struggling to keep pace with themselves.
More tools, not more clarity
For an individual advisory firm, the practical result of this boom is a growing pile of point solutions: one tool for meeting notes, another for portfolio commentary, another for tax scenarios, another for compliance review, another for client communications. Each one is genuinely useful in isolation. Together, they create a new kind of overhead that didn’t exist two years ago — an “AI stack” that needs to be selected, integrated, secured, and maintained, on top of the CRM-and-custodian stack advisors were already juggling.
Industry voices are starting to say the quiet part out loud. As one wealth management executive put it, a single new AI launch is “significant, but not by itself” — it’s part of a wave of tools that will change how advisors work, but only if the wave doesn’t drown the people it’s meant to help.
The compliance surface is multiplying
Every new AI connector is also a new data-sharing question. Which vendor sees client PII? Is there a zero-data-retention agreement? Is the model trained on firm data? Who’s liable if the tool gets something wrong in a regulated recommendation? These aren’t hypothetical questions — they’re already surfacing in industry commentary around recent partnerships, where firms have had to explicitly clarify that account-level data isn’t shared with AI vendors, or that outputs are “insights,” not formal advice.
Multiply that by five, six, or ten point tools, and a firm’s compliance team is now reviewing an entire portfolio of AI vendors instead of one.
Advisors didn’t ask for a bigger stack
The original promise of AI in wealth management was simple: give advisors back the roughly five-sixths of their time currently spent on prep and documentation instead of clients. Somewhere in the last year, that promise turned into a procurement problem — evaluating, licensing, and integrating a growing list of tools that don’t talk to each other.
The firms that come out ahead in this cycle won’t be the ones that adopted the most AI tools. They’ll be the ones that resisted stack sprawl and instead built — or bought — one unified system that does the job the ten separate tools were trying to do.
Unlock the potential of AI-powered transformation.
Written byTim HighlandGroup President – Wealth Management
Updated on
Understanding NIGO, why it costs wealth management firms millions, and how AI-powered onboarding eliminates it at the source
What Does NIGO Mean?
NIGO stands for Not-in-Good-Order. In the wealth management industry, a NIGO occurs when a submitted document, form, or application contains errors, omissions, or inconsistencies that prevent it from being processed. The submission is returned to the submitting party — typically the advisor or the client — for correction before it can proceed.
NIGOs are most common in account opening, account maintenance, transfer forms, and any process that requires structured data submission to a custodian, clearing firm, or processing system. Every NIGO represents a failed submission that must be identified, communicated, corrected, and resubmitted — adding cost, time, and frustration at every step of the process.
Industry estimates suggest that NIGO rates in paper-based wealth management onboarding environments commonly run between 20% and 40% of all submissions — meaning that nearly one in three account applications is rejected before processing even begins.
The True Cost of NIGO in Wealth Management
Direct Operational Costs
Every NIGO event triggers a sequence of operational steps: the processing system or custodian identifies the error, the operations team logs and communicates the rejection, the advisor or client corrects the issue, the form is resubmitted, and the processing queue starts over. Each of these steps consumes staff time, generates operational overhead, and delays account activation — with direct costs estimated at $50 to $100 per NIGO event or more, depending on the complexity of the correction required.
Revenue Delay and Client Experience Impact
Every day an account is stuck in NIGO resolution is a day that client assets are not in the firm’s custody generating advisory fees. For a firm opening hundreds of accounts per month, even a 48-hour average NIGO delay across a 25% NIGO rate represents a measurable drag on revenue. More significantly, clients experiencing repeated correction requests during onboarding begin their advisory relationship with a negative impression that is difficult to reverse.
Advisor Productivity Loss
Advisors who spend time tracking down NIGO errors, calling clients to collect missing information, and resubmitting corrected applications are not meeting with clients, prospecting, or delivering advice. NIGO management is one of the most significant contributors to advisor administrative burden — and one of the most solvable with the right technology.
Custodian Relationship Risk
Custodians track NIGO rates at the firm level. Firms with persistently high NIGO rates may face additional scrutiny, slower processing priority, or operational support consequences. Maintaining a low NIGO rate is not just an internal efficiency goal — it is a factor in the firm’s standing with its operational partners.
NIGO Impact Category
Typical Effect
Scale for a Mid-Size Firm
Per-event operational cost
$50–$100 in staff time per NIGO
$250K–$500K annually at 25% NIGO rate
Account activation delay
2–5 additional business days per NIGO
Weeks of delayed revenue across monthly volume
Advisor time lost
30–60 minutes per NIGO resolution
Hundreds of hours per year across advisor team
Client satisfaction impact
Negative first impression at onboarding
Measurable reduction in early asset consolidation
Repeat submission risk
Corrections sometimes introduce new errors
Cascading NIGO cycles on complex accounts
The Most Common Causes of NIGO
Missing or Incomplete Fields
The single most common cause of NIGO rejections is simply that required fields are left blank. In paper-based and legacy digital environments, there is no mechanism to prevent submission of an incomplete form. The error is only discovered after the custodian or processing system reviews the submission — by which point significant time has already elapsed.
Signature Errors and Missing Authorizations
Many account forms require signatures in multiple locations, with specific date requirements, initials, or joint account co-signer signatures. Missed signatures — even on a single line of a multi-page form — result in rejection of the entire submission. In paper environments, this is a frequent and frustrating source of NIGO events.
Data Format and Consistency Errors
Date fields entered in the wrong format, Social Security Numbers with incorrect digit counts, addresses that do not match identity documents, and beneficiary percentages that do not sum to 100% are all common sources of form rejections. These errors are entirely preventable with real-time validation — but invisible in paper-based submission processes.
Outdated or Incorrect Forms
Custodians and processing firms periodically update their required forms. Advisors using old form versions — whether stored in a desk drawer, a shared drive folder, or a legacy document management system — submit applications on outdated templates that are automatically rejected. In environments without centralized form management, this is a persistently common NIGO source.
Suitability and Regulatory Mismatches
Account applications that request investment products or account types inconsistent with the client’s stated risk tolerance, investment objectives, or regulatory eligibility may be rejected for suitability or compliance reasons. Without automated suitability checks at submission, these errors are only caught downstream — after the form has been submitted and reviewed.
How AI-Powered Onboarding Eliminates NIGO at the Source
The most effective NIGO reduction strategy is prevention — building validation logic into the submission process so that errors are caught and corrected before the form ever reaches the custodian or processing system. AI-powered onboarding platforms achieve this through multiple layered mechanisms:
Real-Time Field Validation
Smart digital forms validate every field as it is completed — checking format, completeness, and logical consistency in real time. Advisors and clients receive immediate feedback when something is missing or incorrectly formatted, rather than discovering the error after submission. Forms cannot be submitted until all validation checks pass, eliminating blank-field rejections entirely.
Intelligent Data Pre-Population
AI-powered onboarding platforms pre-populate known client data from CRM systems, existing account records, and identity verification results — reducing the volume of manual data entry and the associated error rate. When the system already knows the client’s name, address, SSN, and investment profile, the advisor and client only need to confirm and supplement rather than enter from scratch.
Custodian-Specific Requirement Validation
Different custodians have different form specifications, data requirements, and processing rules. Leading platforms maintain current custodian requirement libraries and validate submissions against the specific custodian’s rules before submission — catching custodian-specific rejections before they occur rather than after.
Digital E-Signature with Guided Completion
Digital signature workflows guide signers through every required signature location in the correct sequence, with automatic reminders for co-signer actions and completion tracking. It is structurally impossible to miss a required signature in a properly configured e-signature workflow — eliminating the most common paper-based NIGO category entirely.
Always-Current Form Libraries
Centralized digital form libraries are maintained and updated automatically when custodians and processing firms release new form versions. Advisors always submit on current forms without needing to manage version control manually — removing outdated form submissions as a NIGO source entirely.
How JIFFYAI Drives NIGO Rates Toward Zero
JIFFYAI’s Unified Onboarding solution is purpose-built to eliminate the conditions that produce NIGO events. Real-time validation logic, AI-powered data pre-population, guided digital signature workflows, and pre-built custodian integrations work together to ensure that every submission is complete, accurate, and compliant before it leaves the platform.
NIGO Cause
How JIFFYAI Prevents It
Missing or incomplete fields
Real-time validation prevents form submission until all required fields are complete
Signature errors
Guided e-signature workflow ensures every required signature is captured in sequence
Data format errors
Inline format validation catches SSN, date, and address errors as they are entered
Outdated forms
Centralized, automatically updated form library ensures current custodian versions always
Suitability mismatches
Automated suitability checks flag inconsistencies before submission
Beneficiary percentage errors
Logic validation confirms beneficiary allocations sum correctly before submission
Cross-field inconsistencies
AI cross-field validation catches logical conflicts across the entire application
NIGO Tracking and Analytics
Beyond prevention, JIFFYAI provides real-time NIGO tracking and analytics that allow operations managers to monitor rejection rates by account type, advisor, custodian, and error category. This visibility enables continuous improvement — identifying any remaining error patterns and closing them systematically — and provides the metrics needed to demonstrate operational performance to firm leadership and regulatory examiners.
NIGO rate by advisor — identify individual training needs and coaching opportunities.
NIGO rate by account type — pinpoint form or process design issues specific to certain products.
NIGO rate by custodian — track custodian-specific rejection patterns and address them proactively.
Average resolution time — measure how quickly NIGO events are resolved when they do occur.
NIGO cost per period — quantify the operational cost impact and track ROI from reduction initiatives.
A practical framework for reducing errors, accelerating activation, and delivering a standout first impression
Why Account Opening Matters More Than Most Firms Realize
The new account opening process is the first substantive operational experience a client has with a wealth management firm. Before they receive their first statement, before they see their first portfolio return, before any advisory conversation — they experience the process of becoming a client. That experience sets the tone for the entire relationship.
Despite its importance, account opening remains one of the most error-prone and friction-heavy processes at most wealth management firms. Not-in-good-order (NIGO) rates of 20–30% are common in paper-based environments. Processing times that stretch to weeks erode client confidence. And each error or delay increases operational cost and regulatory exposure.
Research shows that clients who experience a seamless onboarding process are significantly more likely to consolidate additional assets with the same firm within the first 12 months.
Based on our recent experience working with leading wealth firms across different AUM segments and technology landscapes, here are six proven best practices to enhance the efficiency and speed of new client account opening.
Best Practice 1: Digitize the Entire Application Process
Paper applications are the root cause of most NIGO rejections. Fields are left blank, handwriting is illegible, required signatures are missed, and data must be manually re-entered into multiple systems. A fully digital application process uses smart forms that validate entries in real time, pre-populate known data from existing records, and prevent submission of incomplete applications.
Digital applications also create a structured data record from the first interaction, eliminating the downstream problem of converting paper inputs into usable data. Every field captured digitally is immediately available to all connected systems — no re-entry, no transcription errors, no delays.
Best Practice 2: Automate Identity Verification and KYC
Manual identity verification — reviewing physical documents, running watchlist checks, and assembling KYC files by hand — is slow, inconsistent, and creates compliance risk. Automated KYC processes integrate identity verification, AML screening, and CIP (Customer Identification Program) requirements into the account opening workflow itself, completing in minutes what manual processes require days to achieve.
Importantly, automated KYC creates a complete, timestamped audit trail for every check performed — a critical advantage in regulatory examinations. When an examiner asks how a particular client was verified, the answer is a click away rather than a search through filing cabinets.
Best Practice 3: Enable Multi-Account Opening in a Single Session
Many wealth management clients need multiple account types — a taxable brokerage account, a Roth IRA, a joint account with a spouse, a trust account for their estate. Traditional account opening processes require separate applications for each, multiplying the paperwork burden and the opportunity for errors. Modern onboarding platforms allow clients to open all required accounts in a single guided session, with shared data pre-populated across every account type.
This capability is particularly valuable for high-net-worth and ultra-high-net-worth clients with complex financial structures, where the ability to efficiently establish a complete financial relationship is a meaningful competitive differentiator.
Best Practice 4: Integrate Directly with Custodians and Processing Systems
One of the most common sources of delay in account opening is the handoff between the advisory firm and its custodians or clearing firms. When this handoff is manual — involving emailed forms, faxed documents, or portal uploads — it introduces multiple points of failure and creates processing queues that slow account activation.
Pre-built custodian integrations eliminate this problem by transmitting completed account data directly to the custodian’s processing systems upon submission, with automatic status tracking and exception alerts. The account opening process becomes a single, connected workflow rather than a series of disconnected hand-offs.
Best Practice 5: Build in Real-Time Validation and Error Prevention
The most efficient strategy for reducing NIGO rates is not improving the rejection handling process — it is preventing errors from reaching submission in the first place. Real-time validation logic checks every data entry against business rules, regulatory requirements, and custodian specifications as the form is completed, alerting the advisor or client immediately when something needs to be corrected.
Validation Type
What It Checks
Error Prevention Benefit
Field completeness
Required fields are populated before submission is allowed
Eliminates blank field rejections
Data format validation
Date formats, SSN patterns, account number structures
Eliminates format-based rejections
Cross-field consistency
Beneficiary percentages sum to 100%, address matches ID
Validates against specific custodian requirements pre-submission
Reduces custodian-side NIGO rates
Best Practice 6: Measure, Monitor, and Continuously Improve
Account opening performance should be treated as a managed operational metric, not an accepted overhead. Firms that track NIGO rates, cycle times, and processing costs at the application level — and review them regularly — consistently outperform those that treat account opening as a fixed-cost process.
Track NIGO rates by account type, advisor, and application source — to identify systematic error patterns.
Monitor cycle time from submission to account activation — with alerts when specific steps exceed thresholds.
Measure straight-through processing rates — as a leading indicator of automation effectiveness.
Collect client satisfaction data at account opening completion — to capture experience quality signals.
Review custodian rejection data monthly — to identify emerging specification changes or edge cases.
Written byManish PandeyChief GTM & Marketing Officer
Updated on
A practical guide to the compliance frameworks that govern wealth management operations — and how AI-powered platforms help firms meet them confidently
Why Regulatory Compliance Is Central to Wealth Management Operations
Wealth management firms operate within one of the most densely regulated environments in financial services. Every advisory relationship, every client account, every transaction, and every client communication is subject to oversight by one or more regulatory bodies. For broker-dealers, that means FINRA and the SEC. For registered investment advisers (RIAs), it means the SEC or state regulators. For firms handling client data and technology systems, it increasingly means SOC 2 and data security frameworks as well.
Compliance is not optional, and the cost of getting it wrong — in fines, reputational damage, and operational disruption — is substantial. But for firms with the right technology infrastructure, compliance is also an opportunity: to build operational systems that are inherently audit-ready, to create client trust through demonstrable governance standards, and to reduce the manual burden on compliance teams so they can focus on judgment rather than paperwork.
The most successful wealth management firms treat compliance infrastructure not as a cost center but as a competitive asset — one that enables growth, builds client confidence, and reduces operational risk simultaneously.
FINRA: The Self-Regulatory Organization for Broker-Dealers
What FINRA Regulates
The Financial Industry Regulatory Authority (FINRA) is the self-regulatory organization (SRO) that oversees broker-dealers and their registered representatives operating in the United States. FINRA writes and enforces rules governing how broker-dealers conduct business, supervise their registered representatives, communicate with clients, manage conflicts of interest, and maintain required records.
FINRA Rule 4511 (Books and Records) — requires broker-dealers to maintain books and records in a format and timeframe specified by FINRA and SEC rules. Core records must generally be retained for six years; some categories require longer retention periods.
FINRA Rule 3110 (Supervision) — requires broker-dealers to establish and maintain a system to supervise the activities of their associated persons. This includes written supervisory procedures (WSPs), designated supervisors, and documented review processes.
FINRA Rule 2010 (Standards of Commercial Honor) — broad conduct rule requiring members to observe high standards of commercial honor and just and equitable principles of trade in all business dealings.
FINRA Rule 4370 (Business Continuity Plans) — requires broker-dealers to maintain written business continuity plans covering how the firm will respond to significant business disruptions.
Regulation Best Interest (Reg BI) — requires broker-dealers to act in the best interest of retail customers when making investment recommendations, with documentation requirements to demonstrate compliance.
What FINRA Examinations Look For
FINRA conducts routine examinations of broker-dealers to assess compliance with applicable rules and regulations. Examiners review supervisory procedures, sample client files, test transaction records, assess communications practices, and evaluate the firm’s overall compliance culture. The most common examination findings involve deficiencies in supervision documentation, recordkeeping gaps, and inadequate written supervisory procedures.
Firms that maintain digital, searchable, systematically organized records — rather than relying on paper files and manual processes — consistently perform better in examinations because they can respond to examiner requests quickly, completely, and with confidence.
SEC Oversight: Investment Advisers and Broker-Dealers
The Securities and Exchange Commission (SEC) regulates both broker-dealers (directly and through FINRA as the SRO) and registered investment advisers (RIAs). For RIAs with more than $110 million in assets under management, registration with the SEC is required. RIAs below this threshold register at the state level.
Investment Advisers Act of 1940
The Investment Advisers Act governs the conduct of registered investment advisers. Key obligations include the fiduciary duty to act in clients’ best interests, Form ADV disclosure requirements, recordkeeping obligations under the Advisers Act Books and Records Rule (Rule 204-2), and ongoing supervision and compliance program requirements under Rule 206(4)-7.
SEC Examination Priorities
The SEC’s Division of Examinations publishes annual examination priorities that signal areas of heightened regulatory focus. Recent priorities have included cybersecurity practices, the use of technology and AI in investment advice, Environmental, Social, and Governance (ESG) disclosures, and compliance programs at newly registered advisers. Firms operating at the intersection of technology and advisory services — like AI-powered wealth management platforms — should pay particular attention to these priorities.
SOC 2: The Technology Trust Standard for Wealth Management Firms
What Is SOC 2?
SOC 2 (System and Organization Controls 2) is an auditing framework developed by the American Institute of Certified Public Accountants (AICPA) that evaluates how a technology service provider manages and protects client data. A SOC 2 report provides independent, third-party assurance that a firm’s systems and controls meet defined standards for security, availability, processing integrity, confidentiality, and privacy.
Why SOC 2 Matters for Wealth Management
Wealth management firms handle some of the most sensitive personal and financial data in existence. Clients and regulators increasingly expect firms to demonstrate — not just assert — that their technology platforms and data handling practices meet rigorous security and privacy standards. SOC 2 certification provides that independent evidence.
For wealth management firms evaluating technology vendors — including AI solution providers, data aggregation services, and onboarding solutions — SOC 2 Type II certification is a baseline expectation. A Type II report covers an extended period (typically six to twelve months) and assesses not just whether controls are designed appropriately, but whether they are operating effectively over time.
SOC 2 Trust Service Criterion
What It Covers
Wealth Management Relevance
Security
Protection against unauthorized access and data breaches
Client account and financial data protection
Availability
System uptime and performance reliability
Advisor and client access to real-time data and tools
Processing Integrity
Accuracy and completeness of data processing
Transaction processing and data aggregation accuracy
Confidentiality
Protection of confidential information
Client financial data and proprietary firm information
Privacy
Personal information collection, use, and disposal
Client PII handling in compliance with privacy regulations
SOC 2 Type I vs. Type II
A SOC 2 Type I report assesses whether a firm’s controls are suitably designed at a specific point in time. A SOC 2 Type II report goes further, assessing whether those controls operated effectively over a sustained period — typically six to twelve months. For wealth management firm vendor evaluation, Type II is the relevant standard, as it provides evidence of operational effectiveness rather than just design adequacy.
Building a Compliance-Ready Technology Infrastructure
The most effective approach to regulatory compliance in wealth management is not to treat it as a separate function that sits alongside operations — it is to build compliance into the operational infrastructure itself. When every workflow automatically documents the steps taken, every communication is systematically archived, every exception is routed through a defined review process, and every data access is logged and auditable, compliance becomes a byproduct of good operations rather than an additional burden.
Automated workflow documentation — every step of every operational process is timestamped and recorded without manual logging.
Systematic records retention — retention policies enforced automatically by document type, with destruction events logged.
Access controls and audit logs — role-based access to client data with complete logs of who accessed what and when.
Exception workflow management — structured escalation and resolution processes for compliance exceptions, with full documentation.
Real-time supervision monitoring — continuous monitoring of advisor activity and client interactions rather than periodic sampling.
How JIFFYAI Supports FINRA, SEC, and SOC 2 Compliance
JIFFYAI’s Engagement AI platform is built with enterprise-grade security and governance controls designed to support wealth management firms operating under FINRA and SEC oversight. The platform’s unified Data Warehouse maintains complete, auditable records of all client data, transactions, and advisor interactions — enabling firms to respond to regulatory inquiries and examination requests with confidence.
Automated workflow capture across all key platform functions — from client onboarding through account servicing — creates the systematic documentation that FINRA Rule 3110 supervision requirements demand. Role-based access controls, data encryption, and comprehensive audit logging support SOC 2 compliance for firms evaluating JIFFYAI as a technology vendor. The AI Advisor Companion adds a further compliance layer by automatically capturing meeting notes, action items, and client interaction summaries — creating consistent, auditable records of every advisor-client engagement.
Compliance Requirement
JIFFYAI Capability
How It Helps
FINRA Rule 4511 — Books and Records
Unified Data Warehouse with automated document management
All client records retained in searchable, audit-ready format
FINRA Rule 3110 — Supervision
Workflow automation with complete step-by-step audit trail
Every supervisory action documented automatically
Reg BI — Best Interest Documentation
AI Advisor Companion meeting capture and action logging
Client interaction records demonstrating advice rationale
SEC Rule 204-2 — Adviser Records
Comprehensive client data retention across all data types
Complete adviser recordkeeping without manual assembly
SOC 2 — Security and Access Controls
Role-based access, encryption, and full audit logging
Independent-audit-ready security and privacy controls
Written byTim HighlandGroup President – Wealth Management
Updated on
How structured document management practices protect wealth management firms during regulatory examinations and support operational excellence
Why Document Management Is a Strategic Priority
Financial advisors generate and receive an enormous volume of documents in the course of serving clients: account applications, investment policy statements, financial plans, trade confirmations, client correspondence, compliance disclosures, suitability records, and more. How these documents are stored, organized, and retrieved has significant implications for regulatory compliance, operational efficiency, advisor productivity, and — ultimately — client outcomes.
Poor document management is not just a filing inconvenience. It is a regulatory liability. When examiners request records and firms cannot produce them promptly and completely, the consequences range from citation notices to significant fines. When advisors cannot find client documents they need during client interactions, service quality suffers. And when firms undergo advisor transitions or corporate transactions, document chaos can delay or derail the entire process.
Regulatory Requirements for Document Retention
Broker-dealers, registered investment advisers (RIAs), and other wealth management firms operate under detailed document retention requirements established by FINRA, the SEC, and relevant state regulators. These rules specify not just what documents must be retained, but for how long, in what format, and with what controls.
Key retention categories:
Account records — customer account information, agreements, and account maintenance records. Generally retained for 6 years under FINRA Rule 4511.
Business communications — correspondence and communications related to the firm’s business, including email and electronic messages.
Order records and confirmations — records of orders, trade confirmations, and execution documentation.
Financial records — general ledger, trial balances, income records, and expense records.
Compliance and supervision records — supervisory procedures, exception reports, and compliance review documentation.
Digital document management systems that automatically apply retention rules, flag documents approaching their retention limits, and enforce destruction policies reduce the compliance burden of retention management significantly — while providing a defensible audit trail of retention compliance itself.
What Document Audit Readiness Means in Practice
Audit readiness is the ability to respond to a regulatory examination or internal audit request promptly, completely, and confidently. A truly audit-ready firm can produce any requested document within hours, provide complete context for every client interaction, demonstrate systematic compliance with supervision requirements, and show a clean chain of custody for all records.
Achieving this standard requires more than just storing documents. It requires structured metadata that enables search and retrieval, version control that maintains document history, access controls that enforce security while enabling authorized retrieval, and integration with the systems that generate documents so that records are captured automatically rather than depending on manual filing.
The difference between a firm that passes a regulatory examination and one that receives a deficiency notice is often not the underlying compliance record — it is the ability to demonstrate that record quickly and completely.
AI-Powered Document Management: Beyond the Filing Cabinet
Intelligent Document Classification
AI-powered document management systems automatically classify incoming documents by type, client, advisor, and relevant regulatory category — without manual tagging. This ensures that every document is consistently organized and retrievable, regardless of how it entered the system.
Full-Text Search and Contextual Retrieval
Modern document platforms support full-text search across all document content — not just file names or manually applied tags. An advisor or compliance officer can search for a client’s name, an account number, a date range, or a specific term and retrieve all relevant documents instantly, regardless of document type or format.
Automated Retention Policy Enforcement
Retention rules are applied automatically at the document level, with configurable policies by document type and regulatory category. Documents approaching their destruction dates are flagged for review, and destruction events are logged with the date, document type, and approving authority — creating a defensible record of retention compliance.
Integration with Advisor Workflows
Document management delivers the greatest value when it is embedded in the advisor’s daily workflow rather than operating as a separate system. When the advisor desktop, onboarding platform, and servicing tools all automatically file documents to the central repository, the burden of document management shifts from advisors to the platform — and completeness improves dramatically.
How JIFFYAI Integrates Document Management with the Advisor Experience
JIFFYAI’s Engagement AI suite processes all document types — structured forms, PDFs, emails, scanned documents, and voice notes — into a unified Data Warehouse, creating a searchable record of all client-related documentation. Documents generated through the Client Onboarding and Account Servicing workflows are automatically filed with complete metadata, creating an audit-ready record without any manual filing effort.
Document Type
How JIFFYAI Handles It
Compliance Benefit
Account applications
AI extraction and automatic filing with full metadata
Complete, searchable account opening records
Client correspondence
Ingestion and classification from email and messaging
Systematic communication archive
Compliance disclosures
Workflow-driven generation and acknowledgment capture
Documented evidence of required disclosure delivery
Meeting notes and summaries
AI Companion auto-capture from advisor interactions
Consistent interaction documentation without manual entry
Financial plans and proposals
Version-controlled document management with client linking
Complete planning history with change audit trail
Learn how JIFFYAI can help your firm achieve and demonstrate audit readiness across all document types — visit jiffy.ai/wealth-management.
Unlock the potential of AI-powered transformation.
Written byTim HighlandGroup President – Wealth Management
Updated on
Why wealth management firms need a single source of truth — and how AI-powered data aggregation makes it achievable
The Data Problem in Wealth Management
Wealth management firms operate in one of the most data-intensive environments in financial services. Client data flows from custodians, portfolio management systems, CRMs, compliance platforms, document repositories, banking cores, and insurance systems — often in incompatible formats, on different update schedules, and with no central mechanism for reconciliation.
The result is chronic data fragmentation. Advisors work with incomplete information. Operations teams spend hours reconciling inconsistencies. Risk officers lack the comprehensive visibility needed for effective oversight. And the AI and analytics investments firms want to make cannot reach their potential without a clean, unified data foundation.
Data fragmentation is not just an IT problem — it is a revenue problem. Advisors who lack a complete client view miss cross-sell opportunities, deliver inconsistent advice, and lose clients to better-informed competitors.
What Is a Wealth Management Data Warehouse?
A data warehouse in the context of wealth management is a centralized repository that ingests, normalizes, and stores data from across the firm’s technology ecosystem. Unlike operational systems, which are optimized for transaction processing, a data warehouse is designed for analysis — enabling advisors, managers, and executives to query and act on comprehensive information without touching production systems.
Modern wealth management data warehouses go beyond traditional storage. They incorporate AI-driven extraction, real-time and batch processing capabilities, and domain models specifically designed for the complexity of wealth, banking, and insurance data. They support not just structured records but also semi-structured and unstructured data — forms, PDFs, emails, voice notes, and documents of all types.
Key Architecture Components
Universal Domain Model
A universal domain model is a pre-built data schema that maps common wealth management concepts — client, account, household, portfolio, transaction, advisor, product — across all connected systems. Rather than building custom integrations for every data source, firms connect to a single model that normalizes data regardless of source format.
AI-Powered ELT Framework
Modern data warehouses use an Extract, Load, Transform (ELT) architecture where AI automates data extraction from diverse sources, accelerates transformation logic, and enforces data quality rules — reducing the time from data ingestion to actionable insight from days to minutes.
Pre-Built Connector Library
Out-of-the-box integrations using APIs, RPA, and file-based connectors enable plug-and-play connectivity with major custodians, account processing cores, CRM platforms, document management systems, and KYC solutions — without custom development.
Real-Time and Batch Processing
The most sophisticated platforms support both real-time data streaming for time-sensitive advisor and client interactions, and batch processing for high-volume overnight operations — ensuring that the right data is available at the right time for every use case.
From Data Warehouse to Advisor Intelligence
A data warehouse is most valuable not as a technical infrastructure asset but as the engine that powers advisor intelligence. When data is unified, normalized, and accessible, firms can build the workflows, dashboards, and AI capabilities that transform how advisors serve clients.
Data Capability
Advisor Outcome
360-degree client view
Complete picture of every client relationship across all accounts and products
Real-time portfolio data
Instant access to performance, allocation, and risk metrics
Cross-system data reconciliation
Eliminate discrepancies between CRM, custodian, and portfolio data
AI-powered analytics
Predictive insights for rebalancing, cross-sell, and churn prevention
Unstructured data processing
Extract insights from emails, documents, voice notes, and PDFs
JIFFYAI’s Data Warehouse and Data Aggregation Solutions
JIFFYAI’s Data Warehouse and Data Aggregation solutions bring together all data types from across custodians, core systems, CRMs, and document platforms into a single trusted source. Powered by AI-driven automation, they convert raw data into real-time actionable insights and deliver them directly to advisors through a unified interface.
Unified data foundation: delivering a true 360-degree client view across wealth, banking, and insurance.
Seamless no-code integrations: for real-time and batch data flow from all major platforms.
AI-powered extraction and analytics: driving faster and smarter advisor decisions.
Enterprise-grade security and data quality: with built-in governance and compliance controls.
Extensibility to machine learning and data lakes: for advanced predictive analytics and deep storage.
Explore how JIFFYAI can help your advisors overcome data silos and gather growth-oriented insights when and where they need. Visit our Data Warehouse and Aggregation Page.
Power your next growth phase with a unified data foundation
Written byManish PandeyChief GTM & Marketing Officer
Updated on
How AI-powered compliance tools help wealth management firms meet regulatory obligations without overwhelming operations teams
The Compliance Challenge in Modern Wealth Management
Compliance in wealth management has never been more demanding. Regulatory requirements from FINRA, the SEC, state regulators, and international bodies continue to expand in scope and complexity. Supervision obligations require firms to monitor advisor communications, review client interactions, document investment recommendations, and produce comprehensive records on demand — all while keeping pace with a growing advisor and client base.
For most firms, compliance is still largely a manual function. Compliance officers review samples of advisor communications, run periodic exception reports, and chase documentation through email chains and shared drives. This approach is not just inefficient — it is increasingly inadequate. Regulators expect comprehensive, systematic oversight, and manual sampling cannot deliver it.
FINRA and SEC examination findings consistently cite deficiencies in supervision as among the most common and consequential compliance failures at broker-dealers and investment advisers.
What Is Compliance Automation?
Compliance automation is the use of technology to execute supervision and compliance functions systematically, continuously, and at scale — rather than relying on manual review of samples and periodic exception reports. It encompasses automated monitoring of advisor activity, AI-driven exception detection, digital workflow management for compliance approvals, and automated generation of regulatory reports and audit documentation.
Critically, compliance automation does not replace compliance professionals. It gives them better tools — surfacing the exceptions that actually matter, automating the documentation that should not require human time, and enabling compliance officers to focus on judgment-intensive decisions rather than mechanical review.
What Is Digital Supervision?
Digital supervision is the systematic, technology-enabled monitoring of advisor activity and client interactions to ensure compliance with regulatory requirements and firm policies. It replaces or augments manual supervision processes with automated monitoring systems that continuously review activity across all channels — trading, communications, client account changes, and documentation — flagging anomalies and exceptions for compliance review.
Key dimensions of digital supervision:
Communications surveillance — monitoring of advisor-client communications across email, messaging platforms, and recorded calls for policy violations and regulatory red flags.
Trade review and supervision — automated review of trade activity for suitability concerns, concentration risks, and pattern anomalies.
Account activity monitoring — continuous review of account changes, withdrawals, and transfers for signs of unauthorized activity or elder financial abuse.
Documentation compliance — verification that required documentation — investment policy statements, suitability records, disclosure acknowledgments — is present and current for every client.
Exception workflow management — structured process for reviewing, investigating, and resolving flagged compliance exceptions with full audit documentation.
Building an Audit-Ready Compliance Infrastructure
Regulatory examinations test not just whether a firm has complied with rules, but whether the firm can demonstrate that compliance — with documentation, timestamps, approval records, and evidence of systematic oversight. An audit-ready compliance infrastructure is one where every relevant action, decision, and communication is automatically recorded, organized, and retrievable.
Compliance Requirement
Manual Approach
Automated Approach
Supervision documentation
Manual log entries and file assembly
Automatic capture of all supervisory actions with timestamps
Exception identification
Periodic sample reviews
Continuous real-time monitoring with AI anomaly detection
Regulatory report generation
Manual data compilation
Automated report generation from live data
Communication archiving
Email exports and folder organization
Systematic capture and indexing of all communications
Examination response
Days of manual record retrieval
Instant retrieval of complete, organized compliance documentation
How JIFFYAI Supports Compliance and Supervision Workflows
JIFFYAI’s Engagement AI solution suite supports compliance automation through several integrated capabilities. The AI Advisor Companion automatically captures meeting notes, action items, and client interaction summaries — creating consistent, auditable records of advisor-client engagement. Workflow automation ensures that compliance-required steps in account opening, servicing, and advisor transitions are never skipped, with every action documented and timestamped.
The unified Data Warehouse provides the data foundation for compliance analytics — enabling compliance teams to monitor activity patterns across the entire book of business, identify anomalies, and generate regulatory reports without manual data assembly. And because all data flows through a single normalized platform, compliance information is always consistent and complete — regardless of which system originated the underlying transaction.
Learn more about how JIFFYAI can help your firm overcome compliance hurdles with the power of AI. Visit Risk and Compliance.
Explore how JIFFYAI can help your firm overcome compliance hurdles with the power of AI